

· AFX Research
Title Search for Property With an Agricultural Exemption
The exemption cuts the tax bill now and creates a recapture liability that attaches to the parcel rather than the owner. What the assessor holds, and the recorded restrictions that sometimes come with it.
Table of Contents
Agricultural use assessment is one of the best deals in property tax, and it comes with a tail that follows the land. Changing the use triggers a rollback — recapture of the tax savings for a run of past years, plus interest in many states — and the liability attaches to the parcel rather than to the person who claimed the exemption.
A buyer planning to develop land currently assessed as agricultural inherits that bill.
What the exemption actually does
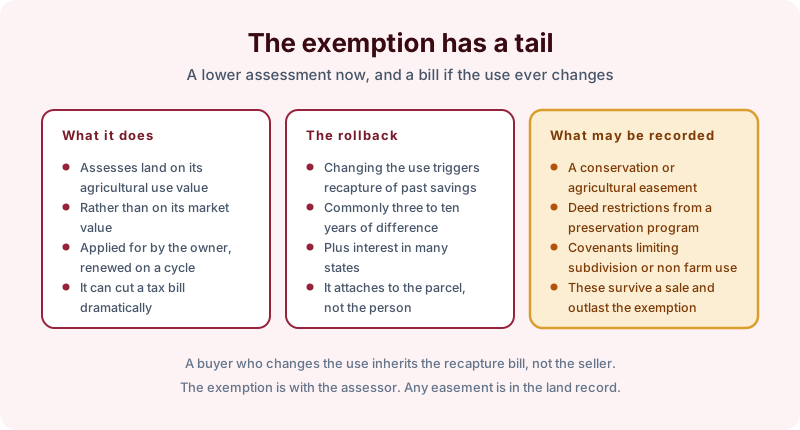
It assesses the land on its agricultural use value rather than its market value, which on urban-fringe land can be a difference of an order of magnitude. The owner applies for it, it renews on a cycle, and it requires the qualifying use to continue.
It is an assessor’s classification, not a property interest. It does not appear in the land record, and a title search will not report it.
The rollback
This is the part that belongs in a purchase decision. Converting the land to a non-qualifying use — subdividing, building, or simply ceasing to farm — triggers recapture of the difference between what was paid and what would have been paid, commonly for three to ten years depending on the state, frequently with interest.
Because the liability runs with the parcel, the timing of the sale rarely matters. A buyer who changes the use pays it, even where the savings were enjoyed entirely by the seller. It is worth quantifying before the offer, not after.
What may be recorded alongside it
Here the title search does real work, because a separate and permanent restriction is sometimes attached to the same land.
A conservation or agricultural easement, sold or donated to a land trust or a government program, permanently limiting development. Deed restrictions from a farmland preservation program, which frequently paid the owner for exactly that limitation. Covenants restricting subdivision or non-farm use.
These are not the exemption. They are recorded property interests that survive every sale, outlast the tax classification entirely, and can make the development that triggered the rollback impossible anyway. That is the same mechanism described in deed restrictions and your title search.
What to order
A full chain search rather than a current owner search, because preservation easements and program restrictions are frequently decades old and sit well back in the chain. Ask for recorded instruments in full rather than summaries, since the scope of an agricultural easement is in its text.
Then ask the assessor separately for the exemption status, the rollback exposure and the years at risk. A records search reports what was recorded and indexed as of the day it was run, and the tax classification is not a recorded matter.
The bottom line
Two different things travel with agricultural land and only one of them is in the deed records. Search the chain for easements and covenants, and ask the assessor what changing the use would cost. Compare the available searches and order online, or ask us what term fits a parcel with a long farming history.